Choosing the right jurisdiction is one of the key decisions when launching a regulated payment or e-money business in the European Economic Area.
In this webinar, we will explore three popular EEA jurisdictions for Payment Institution (PI) and Electronic Money Institution (EMI) licensing: Latvia, Malta and the Netherlands.
Three legal experts specialising in financial regulation in their respective jurisdictions will provide a practical overview of the licensing environment in each country, including:
PI and EMI licensing options and regulatory framework
Key licensing and capital requirements
Local presence, management and operational requirements
Application process and expected timelines
Key considerations when choosing a jurisdiction
Practical aspects of preparing and submitting a licence application
The webinar will help fintech founders and existing financial businesses better understand the differences between the three jurisdictions and assess which option may be more suitable for their business model and expansion plans.
AGENDA
Presentation 1: PI and EMI licensing in the Netherlands
The presentation will provide an overview of PI and EMI licensing in the Netherlands, including key licensing and capital requirements, local presence and management expectations, and the application process and expected timelines.
Jan Christiaan Hagen has hands-on experience supporting DNB EMI licence applications from company inception through the full licensing process. His work includes regulatory engagement, application preparation and managing follow-up questions from DNB throughout the authorisation process.
Presentation 2: PI and EMI licensing in Malta
The presentation will cover the main aspects of obtaining a PI or EMI licence in Malta, with a focus on regulatory and capital requirements, local operational substance, management requirements and the key stages of the application process.
Speaker
Dr. Kelly-Dominic Fenech
Partner, Advapay Malta
Short bio:
Dr. Kelly-Dominic Fenech is an advocate specialising in financial services and the FinTech sector. He has been recognised in the Chambers and Partners FinTech Guide for more than five consecutive years and is currently ranked in Band 2.
Presentation 3: PI and EMI licensing in Latvia
The presentation will explore the PI and EMI licensing framework in Latvia, including capital and licensing requirements, local presence and operational expectations, and the practical process and timeline for submitting an application.
Speakers
Māris Liguts
Partner, Attorney-at-Law, GLIMSTEDT
Short bio:
Māris Liguts is a Latvian attorney-at-law specialising in banking and finance, financial regulation, licensing, AML compliance, corporate law and cross-border transactions. He advises clients on regulatory and corporate matters related to financial services and market entry.
Valters Diure
Partner, Attorney-at-Law, GLIMSTEDT
Short bio:
Valters Diure advises clients on banking and finance, financial regulation, capital markets, aviation finance and cross-border transactions. His practice combines regulatory expertise with experience in complex financial and transactional matters.
Registration
Advapay at stake:
How can Advapay can assist you in launching your fintech, payment or crypto business?
Canada’s MSB landscape is changing. FINTRAC is paying closer attention to MSB registration process, business addresses, operational presence and compliance readiness. At the same time, some MSBs are facing registration revocations or unexpected regulatory issues.
In this webinar, Advapay will explain what is currently happening in the Canadian MSB market, what registered and prospective MSBs should pay attention to, and what companies can do if their MSB registration is at risk or has already been revoked. We will also briefly cover the current regulatory landscape concerning PSPs in Canada.
The second part of the webinar will introduce Advapay’s new solution for MSB companies that need access to international payment rails, including accounts, SEPA, SWIFT and payouts in multiple local currencies. We will explain which companies it is designed for, what services it can support, and how it may help registered MSBs access the infrastructure needed to operate and scale.
Register and watch online!
Webinar agenda
PRESENTATION 1
Canada MSB registration update — what is changing?
Anastasiia Shamshyna, Head of Regulatory Affairs
Key topics:
🔹Current trends in Canadian MSB registration with FINTRAC 🔹FINTRAC’s approach to new MSB registrations 🔹How long MSB registration process takes in practice 🔹FINTRAC’s increased scrutiny of the business address and local presence requirements 🔹Why FINTRAC may ask about the business function behind the registered address 🔹MSB registration revocations and what to do if your MSB is at risk or has been revoked 🔹Risks connected with outdated contact details on file with FINTRAC 🔹Current trends in Canadian PSP registration with the Bank of Canada under RPAA
PRESENTATION 2
Introducing MSBgate — a new infrastructure solution for MSB companies
Ihor Kreshschenko, Chief Executive Officer at MSBgate
Key topics:
🔹The infrastructure challenge for Canadian MSBs 🔹Introducing MSBgate: one platform for accounts, safeguarding and payments 🔹Accounts, payment rails and FX capabilities, crypto on-ramp and off-ramp 🔹Solution for registered MSB and agency scheme 🔹Use cases and payment flows supported by MSBgate 🔹Safeguarding considerations 🔹Compliance by design 🔹Who can onboard and what are the main requirements? 🔹From application to live operations
Register and watch online!
Advapay at stake:
How can Advapay can assist you in launching your fintech, payment or crypto business?
Entering the US fintech market requires careful planning, regulatory understanding and the right banking strategy. In this webinar, our experts will explain how fintech companies can establish a compliant presence in the United States through MSB USA registration (FinCEN), the implementation of a robust compliance framework and a bank-ready operating model.
The session will provide a practical overview of the MSB USA registration landscape, including registration requirements, compliance obligations and banking considerations. Participants will learn how fintech companies can work with sponsor banks, leverage existing licensing structures and accelerate market entry without obtaining individual Money Transmitter Licences in every state.
The webinar will also explore how ready-made fintech infrastructure, core banking technology and compliance solutions can significantly reduce time to market and support a scalable US expansion strategy.
Agenda
Welcome and introduction
Introduction to the webinar programme, speakers and key considerations for fintech companies entering the US market.
Presentation 1: US MSB registration, compliance and banking readiness
Topics covered:
U.S. Compliance Program Overview
Understanding MSBs and Money Transmitter Licensing
Understanding Customer Types (Business VS Indviduals) and Transaction Flows
U.S. Market Entry Options:
Sponsor Bank Partnership (most common approach)
MSB + Sponsor Bank
MSB + State Money Transmitter Licenses (MTLs)
Bank Acquisition / Charter
Typical Timelines and Key Considerations
Presentation 2: Accelerating launch with fintech infrastructure
Presented by Hamid Najafi, Advapay
Topics covered:
Core banking and wallet infrastructure
How ready-made technology can reduce time to market
Building an operational fintech platform from day one
Q&A
Questions and answers with both speakers.
Registration
Advapay at stake:
How can Advapay can assist you in launching your fintech, payment or crypto business?
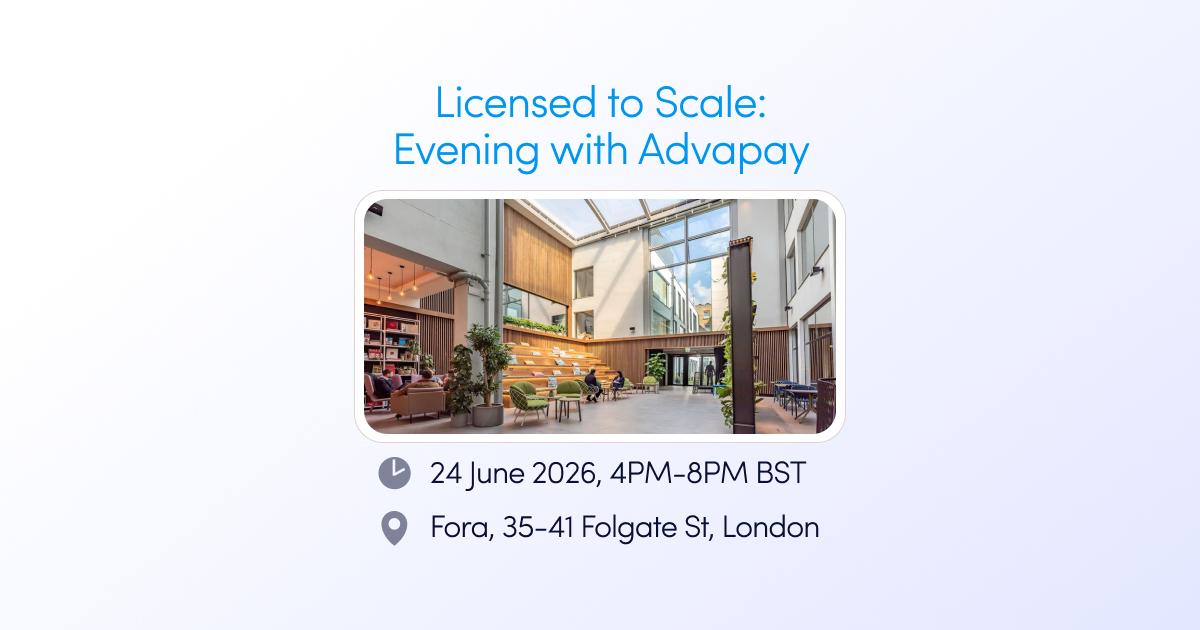
Informal fintech event in London for payment and e-money professionals and founders: wine, nibbles, and conversations, not a sales pitch. Spend it with ambitious people building and licensing fintechs in the UK and beyond.
We’ll talk through EMI/PI licensing in the UK and other jurisdictions, and give a first look at the new Macrobank safeguarding module, built for the FCA’s CASS 15 regime.
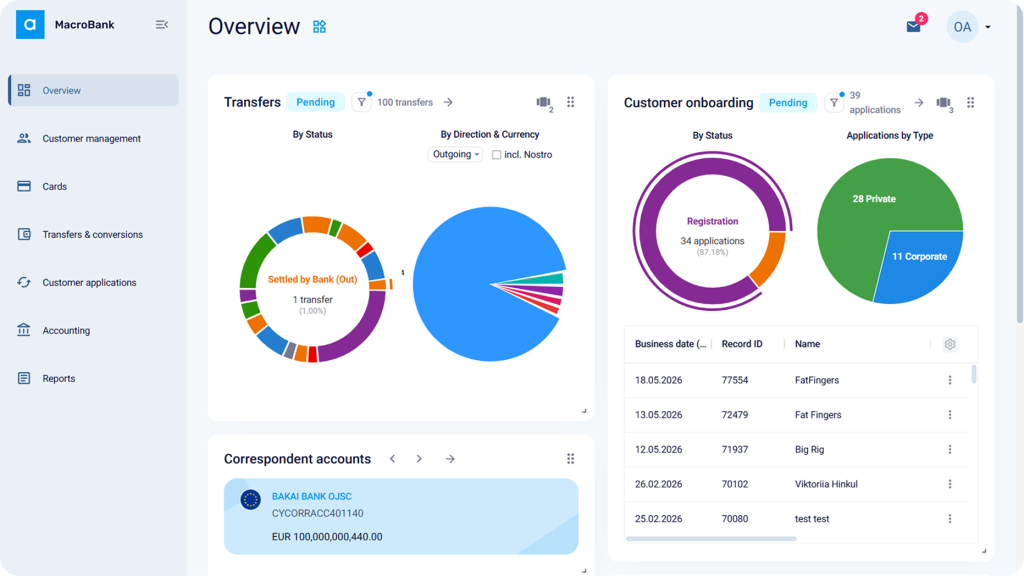
Advapay is introducing Macrobank 3.1 — a major core banking platform upgrade designed to help fintech companies, digital banks, EMI, PI, and crypto businesses scale with greater speed, flexibility, and operational resilience.
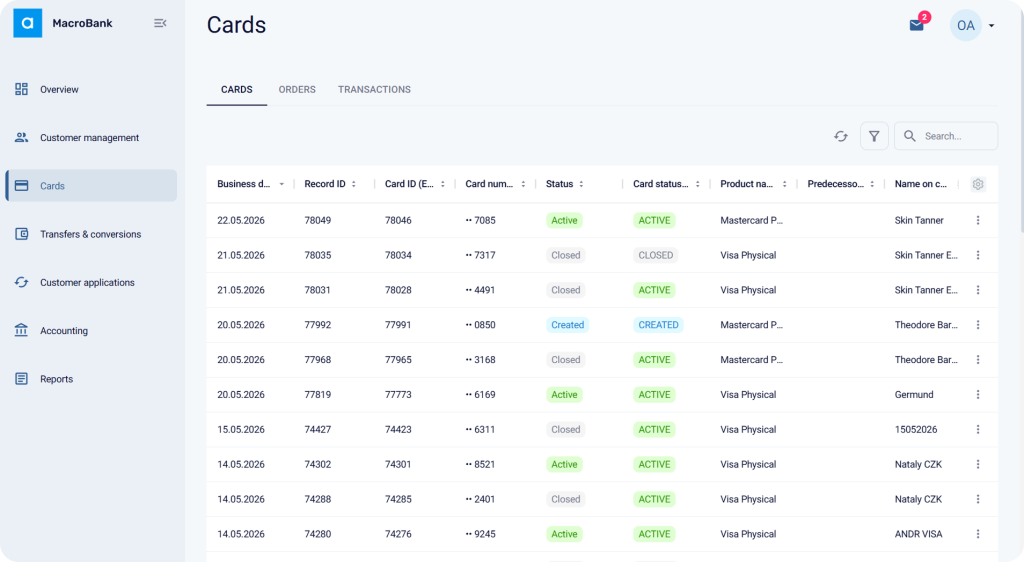
This release introduces significant infrastructure improvements across the platform and launches our brand-new Card Management Module, giving businesses more flexibility in building and managing card programmes within a single ecosystem.
Built for modern fintech infrastructure
Macrobank 3.1 core banking platform upgrade delivers measurable improvements in platform performance, reliability, and scalability.
With a modernised runtime and distributed caching architecture, the core banking platform now provides faster API responses, lower database load, and a smoother operational experience across both client and operator environments.
The release also strengthens system resilience through improved messaging architecture and enhanced event-driven synchronisation, helping reduce delays, duplication issues, and operational bottlenecks.
Under the hood, Macrobank 3.1 is powered by a modern technology stack, including: • .NET 10 • Apache Ignite • RabbitMQ • OpenTelemetry • Kubernetes-ready infrastructure
These improvements create a more stable foundation for growing fintech operations and high-volume transactional environments.
The module enables fintech companies to launch and manage card programmes directly within the Macrobank ecosystem, simplifying operations and improving flexibility.
With the new module, businesses can: • issue, activate, block, replace, and close cards, • manage the full card lifecycle from a single platform, • connect different card issuing providers through a flexible integration layer, • switch providers without rebuilding infrastructure, • securely manage sensitive card operations across services.
The module is designed to support scalable card operations while maintaining operational control and flexibility.
Full transaction and authorisation visibility
Macrobank 3.1 allows businesses to store all transactions and authorisations directly within the platform database, providing full operational visibility across payment flows and card operations.
This enables companies to: • maintain detailed analytical accounting records within the system, • perform reconciliation processes more efficiently, • identify discrepancies and operational mismatches faster, • improve financial and operational oversight, • deliver higher-quality customer support through complete back-office transaction visibility.
By centralising transaction and authorisation data within Macrobank, operations, compliance, and support teams gain better control over payment activities and faster access to operational information.
Smarter workflows for real operational complexity
Macrobank 3.1 significantly expands workflow capabilities across the platform.
The new release introduces triple the workflow branching logic, allowing businesses to better model approvals, exceptions, operational rules, and edge-case scenarios.
These improvements help teams automate more complex operational processes while maintaining transparency and compliance controls.
Extended crypto and AML capabilities
Macrobank 3.1 also extends support for multi-currency and crypto operations.
The platform now offers improved consistency for crypto transaction handling across services, creating a clearer operational structure and easier reconciliation processes.
The release additionally introduces enhanced AML functionality, including blacklist import capabilities for faster and more accurate compliance checks.
Flexible deployment models
Macrobank is designed to adapt to different business models and operational requirements.
Companies can choose between: • SaaS deployment, • software licensing, • or full source-code ownership.
Combined with ready integrations and a modular architecture, Macrobank provides fintech businesses with a scalable foundation for long-term growth.
Core banking platform upgrade: built for fintech growth
Macrobank 3.1 is more than a platform upgrade — it is a step towards more resilient, scalable, and launch-ready fintech infrastructure.
Whether you are building a digital banking platform, expanding payment operations, launching card programmes, or integrating crypto functionality, Macrobank 3.1 provides the flexibility and operational stability needed to support growth.
Ready to see Macrobank 3.1 in action? Contact our team to book a demo
Join our webinar focused on the UK market and how to launch a Payment Institution (PI) or E-Money Institution. During the session, we will discuss the current regulatory and operational environment, UK licensing considerations, safeguarding reconciliation expectations, and practical insights for companies launching or scaling payment businesses in the United Kingdom.
Agenda
Opening & Introduction
Introduction to the webinar “How to Launch, Scale & Operate a Payment or E-Money Institution in the UK”, speakers, and key discussion topics.
Speaker
Conor Dignan, Sales Executive, Advapay UK
Presentation 1: The UK Fintech and Regulatory Environment
Overview of the current UK market landscape for Payment and E-money Institutions, including operational realities, market expectations and how to launch Payment and E-money Institution in the UK.
Speaker
Gary O’Brien, Managing Director, Advapay UK
Presentation 2: E-Money and Payment Institution Licensing in the UK
Presentation 3: Safeguarding and Reconciliation Expectations in the UK
Practical guidance on safeguarding obligations, reconciliation processes, operational controls, and regulatory focus areas for Payment Institutions and E-money Institutions in the UK.
Speaker
Oliver Roberts, Compliance Officer, Advapay UK
Registration
If you are planning to launch a Payment Institution or E-Money Institution business in the UK, Advapay UK can support your company with an end-to-end fintech ecosystem designed for payment companies, fintechs, and digital banking solutions.
Advapay solutions to launch a Payment and E-Money Institution business in the UK
• Core Banking and crypto-fiat wallet software • Assistance with Payment Institution and E-Money Institution licensing in the UK • Compliance and AML support services • Safeguarding and reconciliation solutions • Banking integrations and payment infrastructure • API integrations and fintech ecosystem setup
Contact us to discuss your business model and launch your fintech solution in the UK market.
In industries like fintech, crypto, online gaming, and trading, AML and KYC tools are a must to prevent fraud and stay compliant with legal requirements.
If your company is expanding in one of these industries, choosing the right AML and KYC provider makes a big difference. Here’s a look at some of the top names in 2026. Some of them are trusted providers we work with and are already integrated into our core banking platform.
Veriff
Based out of Estonia, Veriff is widely known for its fast, user-friendly identity verification and fraud prevention tools. It’s ideal for fintechs seeking a seamless onboarding experience coupled with high accuracy in verifying users worldwide.
Key services:
AI-powered ID verification
Biometric facial recognition
Liveness detection
Document checks across 230+ jurisdictions
Automated fraud detection and risk scoring
Real-time decision-making and compliance reporting
Veriff builds its reputation for delivering an intuitive user experience without compromising compliance. Its fraud detection engine is constantly improving, identifying fake documents, deepfakes, and stolen identities early, before they become a threat. For fast-scaling fintechs on the rise, Veriff is often the top pick. More: veriff.com
Sumsub delivers a full, end-to-end compliance platform that covers everything from identity verification to transaction monitoring and Travel Rule compliance for crypto businesses. It’s known for being highly configurable and is internationally friendly.
Key services:
KYC (individual) and KYB (business) onboarding
Biometric and liveness verification
AML screening (sanctions, PEP, watchlists)
Ongoing transaction monitoring
Travel Rule compliance support
Customisable risk-based decision engine
For companies looking to grow across borders, Sumsub is the ideal choice. This is because Sumsub supports over 14,000 document types from 220+ countries. In particular, their automated workflow helps teams focus solely on cases that truly need attention. In 2025, their fraud analytics and dynamic risk scoring tools are more powerful than ever. More: sumsub.com
Cyprus-based Complytek is popular with financial institutions, forex companies, and gaming operators seeking a comprehensive AML suite with strong case management capabilities.
Key services:
KYC and AML platform
Transaction monitoring and alerting
Sanctions, PEP, and adverse media screening
Client risk profiling and scoring
Suspicious activity reporting (SAR)
Regulatory audit trail and reporting tools
Complytek focuses a lot of its attention on helping companies keep audit-readiness while meeting the expectations of regulators like CySEC and ESMA. Its workflow tools make it easy to build, assign, and close compliance cases, complete with clean data logs and reporting capabilities. In 2025, their machine learning module help detect more sophisticated forms of transaction manipulation. More: complytek.ai
iDenfy provides a full-service identity verification and fraud prevention platform designed to help businesses meet global KYC, AML, and KYB compliance requirements and maintain a smooth onboarding experience. The platform combines AI-driven document verification, biometric authentication, and automated risk analysis to help companies verify business users remotely, reduce fraud, and comply with time-consuming regulatory obligations.
Key services:
KYC identity verification with document authentication
Biometric facial recognition and liveness detection
KYB (Know Your Business) verification and UBO checks
AML screening, including sanctions, PEPs, and adverse media
Fraud detection and risk assessment tools
Automated compliance workflows and manual review reports
For companies operating in regulated industries such as fintech, iGaming, crypto, and marketplaces, iDenfy offers a scalable compliance infrastructure that helps streamline onboarding and minimize operational workload for compliance teams. The platform supports identity documents from 200+ countries and territories and uses the latest AI-powered verification technology tools to fight against digital fraud and only approve legitimate users. More: idenfy.com
AMLYZE
AMLYZE provides an integrated AML/CFT compliance platform designed to help financial institutions and regulated businesses detect financial crime, automate compliance processes, and manage regulatory risks. The platform combines real-time transaction monitoring, automated customer risk assessment, advanced screening, and investigation tools in a single system.
Key services:
Real-time and retrospective transaction monitoring
Automated customer risk assessment and scoring
AML screening, including sanctions, PEPs, and adverse media
Payment screening and suspicious transaction detection
AML investigations, alert handling, and case management
Automated compliance workflows and SAR/STR reporting
For banks, payment institutions, fintechs, crypto businesses, and other regulated companies, AMLYZE offers a scalable solution to streamline AML/CFT operations, reduce false positives, and minimise manual workload. Its configurable rules and automated monitoring tools help compliance teams identify suspicious activities, manage customer risks, and meet evolving regulatory requirements. More: amlyze.com
Ondato
Lithuania’s Ondato offers a straightforward, user-friendly compliance platform that suits startups and established financial firms alike. Their onboarding flows are clean, handling both individuals and businesses with equal efficiency.
Key services:
Digital identity verification (video, photo, e-signature)
KYB verification for companies and UBOs
Risk-based scoring and compliance rules
Sanctions and adverse media screening
Workflow automation and audit logs
Face and liveness detection
Ondato shines as a strong option for teams looking for a compliant onboarding process without heavy development resources. Their KYB capabilities have expanded greatly, making it easier for companies to verify business customers and comply with requirements under AMLD5 and FATF. More: ondato.com
Salv
Salv has carved out a unique space in the market. Rather than offering just another standalone AML suite, Salv stands out by delivering financial institutions with a platform to collaborate in real time and fight financial crime together, something that is especially effective across markets that have a high fraud rate.
Key services:
AML transaction monitoring
Customer risk scoring engine
Sanctions, PEP, and adverse media screening
Real-time intelligence sharing via the “Bridge” platform
API integrations for compliance systems
Its Bridge network is what really sets Salv apart. This feature allows institutions to securely flag and share suspicious behaviour throughout a network of regulated entities. Essentially, you’re not fighting fraud alone — you’re part of a larger shield. This unique collaborative approach is proving to be a game-changer for many banks and EMIs across Europe. More: salv.com
Chainalysis
Chainalysis has emerged as the industry standard when it comes to crypto transaction monitoring and blockchain forensics. Government agencies, exchanges, and custodians depend on its tools to trace and analyse on-chain activity.
Key services:
Blockchain transaction monitoring (KYT)
Wallet attribution and address labelling
Risk scoring for crypto wallets and transactions
Investigation platform for on-chain tracing
Sanctions and illicit wallet detection
API for real-time blockchain compliance
Chainalysis is indispensable for any serious crypto business. In 2025, Chainalysis continues to refine its data attribution and add support for new chains. Their tools detect suspicious behaviour and help institutions understand why a wallet is high risk by tracing it back to known hacks, mixers, darknet activity, or sanctioned entities. More: chainanalysis.com
Shufti Pro
Shufti Pro stands out for its global reach, multilingual support, and rapid onboarding capabilities. It is frequently used in fintech, healthcare, e-commerce, and Web3 platforms, all because of its fast, multi-language verification.
Key services:
KYC and KYB verification
Face recognition and biometric verification
Document authentication in 150+ languages
Sanctions, PEP, and watchlist screening
No-code onboarding workflow builder
Real-time fraud detection
In 2025, Shufti Pro expanded its developer tools — including SDKs and no-code widgets — letting small startups roll out verification in days rather than weeks. Their pricing model is flexible too, making it a go-to choice for high-volume, cost-sensitive businesses. More: shuftipro.com
AMLBot
AMLBot serves as a crypto compliance tool designed for rapid and straightforward wallet and transaction screening. It’s become a trusted partner for smaller crypto exchanges, OTC desks, and DeFi apps aiming to stay compliant without requiring a full AML department.
Key services:
Risk scoring of crypto wallets and transactions
Screening for ties to darknet, scams, and mixers
Sanctions (OFAC, EU, UN) and watchlist screening
AML compliance reports for audit or licensing
API access for automated compliance checks
AMLBot is especially appealing because of its simplicity. Enter a wallet address, and you instantly get a full breakdown of its risk profile. In 2025, the platform introduced new blockchain support and upgraded its reporting features, making it more valuable for projects that require lightweight, crypto-specific compliance. More: amlbot.com
Seamless Integrations with Our Core Banking Software
Veriff, Salv, Sumsub, Complytek, Chainalysis, Ondato, Shufti Pro, and AMLBot — are already integrated into our core banking platform. Pick the compliance partner that suits your business best, without worrying about setup delays or complex technical work.
Advapay at stake:
How can Advapay can assist you in launching your fintech business?
Join our webinar to learn how fintech companies can successfully launch and scale in Switzerland — one of Europe’s most respected and innovative financial centres.
Experts from Advapay, Dukascopy Bank, and Keytec will share practical insights on licensing, compliance, banking setup, and payment infrastructure, along with first-hand experience of operating in the Swiss market.
PROGRAMME
Presentation 1: Authorisation for the Swiss market with SRO Membership
The speaker: Justin Friedrich, Partner, Advapay
Gain a clear understanding of the Swiss regulatory landscape and available pathways for fintech companies:
Overview of key licensing routes for fintechs
SRO membership explained
About Justin Friedrich: Justin Friedrich is Advapay’s Swiss partner. He specialises in SRO affiliation and AML outsourcing for crypto-asset service providers (VASPs) and financial intermediaries. He supports companies in establishing regulated operations in Switzerland, guiding them through the full SRO membership process, AML framework design, and ongoing compliance management.
Presentation 2: Swiss banking ecosystem for future SRO members
The speaker: Alex Suhobokov, PhD, CFA, FRM, Senior VP, Head of Fintech
This presentation outlines the Swiss banking ecosystem, how to select suitable banking partners, and the key requirements for successful account opening.
Overview of the Swiss banking landscape and realistic banking options for fintech and SRO members
Types of bank accounts required and their role in business operations
Key onboarding requirements and expectations from Swiss banks
Factors that increase the chances of successful account opening
Practical examples of banking setups and use cases
About Alex Suhobokov: Alex is a seasoned finance executive and fintech pioneer with over 23 years of experience across the banking, regulatory, and academic sectors. He currently serves as Senior Vice President and Head of Fintech at Dukascopy Bank SA in Switzerland, where he leads the digital and institutional banking divisions.
A specialist in bridging the gap between traditional finance and decentralised technology, Alex spearheaded the creation of the first-ever cryptocurrency issued by a regulated bank. He manages a multinational team, overseeing the development of API-driven banking infrastructures, BaaS models, and institutional fintech fiat/crypto ecosystems. Beyond his executive role, Alex is actively involved in the Swiss regulatory landscape via the Crypto Valley Association (CVA) and other local stakeholders.
Alex holds a PhD in Finance from Adam Smith Business School, University of Glasgow and an MBA in Banking from the University of London. His expertise is backed by premier professional designations, including CFA, FRM, and CAMS. He is also the founder of the Riga Fintech Club and the London Fintech Club, informal networking organisations that bring together Fintech industry professionals.
Presentation 3: Launching a Swiss fintech: key insights, common mistakes, and operational realities
The speaker: KEYtec
Keytec will share practical insights from their experience launching services and operating in the Swiss financial market. The session will focus on key considerations for new fintech businesses and how to successfully establish and scale operations in Switzerland.
This webinar will guide you through the real process of opening bank accounts for MSBs and Fintechs — from regulatory setup to becoming fully operational. We will focus on what banks actually expect, common mistakes, and how to build a bank-ready business.
What’s included:
🔹Key banking infrastructure required for MSBs (accounts, payment rails, safeguarding) 🔹How banks evaluate MSBs: business model, flows, clients, and risk profile 🔹Typical reasons MSBs are rejected and how to avoid them 🔹Step-by-step overview of the bank onboarding process 🔹Practical checklist to become “bank-ready” before applying
Speakers:
Karine Papikian Head of Account Opening Advapay Canada
Michael Stahl Senior Compliance Officer Advapay Canada
Register for our on-demand webinar and watch it at your convenience!
Overview
In our webinar “Launching a crypto business in 2025–2026: where to get licensed and how to build a product”, Advapay’s team will outline licensing and registration options for crypto businesses, compare leading jurisdictions, and demonstrate software for crypto-fiat wallets. We’ll cover realistic timelines, typical costs, banking and safeguarding considerations, and the core platform modules.
Programme
Welcome & context
Presentation 1: Jurisdictions for crypto businesses
Comparison across key regions (EEA, Switzerland, Canada)
Decision matrix: time, cost, supervision, product and business considerations
Presentation 2: Software for crypto-fiat wallets: from MVP to scale
Must-have features
Integrations map
Security & resilience
Short demo
Presentation 3: Launching a crypto-fiat wallet business — timeline & budget framework from licensing to launch
Q&A
Key takeaways
A short list of jurisdictions matched to crypto business models
A clear view of the mandatory compliance stack
A practical software blueprint
A timeline and budget framework from licensing to first revenue
Register and watch now!
Before we open WhatsApp
Please provide a few details so we can route your request properly.